Crypto card, neobank or processor account blocked: causes and appeal steps
Status: Published: Last reviewed: Editorial policy
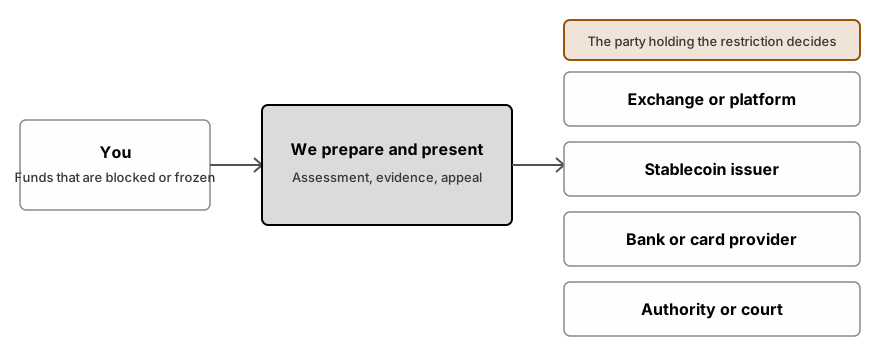
Risk rules, not judgment about you, drive most blocks. A bank, card issuer or processor flags crypto-linked accounts when its automated checks trigger: unexplained origin of funds, a category rated high-risk, a spike in chargebacks, or inbound transfers from an exchange it blacklists. The control stays with the provider. The path forward: a written, precise reply to each question the provider raised, with documents attached. We help you draft that appeal. No service can force a provider to reopen an account.
Need a case detail checked? Send it here:
What we do
- Read the notice, identify the trigger
We review the emails, in-app messages and terms you were given. A provider usually states only a category. We compare that category with your recent transfers, top-ups and activity to identify the rule most likely to have fired.
- Find the cause: risk flag, chargebacks, or category
A funds query, a chargeback ratio and a risk category label are three different questions with three different answers. We identify which trigger applies to your case, so your reply goes to the actual question instead of the wrong one.
- Assemble the evidence pack
Collect bank statements, exchange exports, invoices, contracts and proof of wallet ownership, then arrange the inputs into one consistent pack a reviewer can check in minutes. We coordinate this collection and check that every document supports the same account record.
- Draft the appeal using the provider's own wording
Write a short, factual appeal that cites the block reference, answers each question asked and attaches the matching evidence. We prepare this draft. For business accounts it also covers refund policy, dispute handling and card descriptors.
- When the first channel stalls, escalate
If the standard channel stops moving, the next step is the provider's formal complaint route. Where your jurisdiction has a regulator or ombudsman, we help you file there. Where the amount justifies it, we involve an independent lawyer.
How a case runs
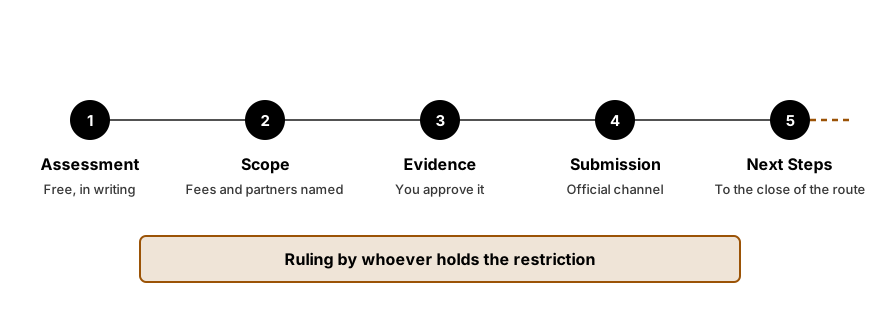
- Free initial review
Send us what was blocked, including the notices you received. We reply in writing with three outputs: whether we can take the case, the likely trigger, and the inputs we would need from you.
- Scope in writing, plus fee
If we proceed, you receive the scope, the fee model and the list of independent specialists in writing first. No payment happens before that document is agreed.
- Evidence gathering
Submit documents via a secure channel. We inspect them for missing items, inconsistent dates and contradictions before any material leaves your hands.
- Filing the appeal
The appeal is filed through the provider's official channel. You get a copy and the ticket reference, so each later message can be linked to it.
- Next Steps
We monitor the reply, assist with follow-up questions, and state plainly when the case has reached the limit of what can be done.
Inputs to prepare
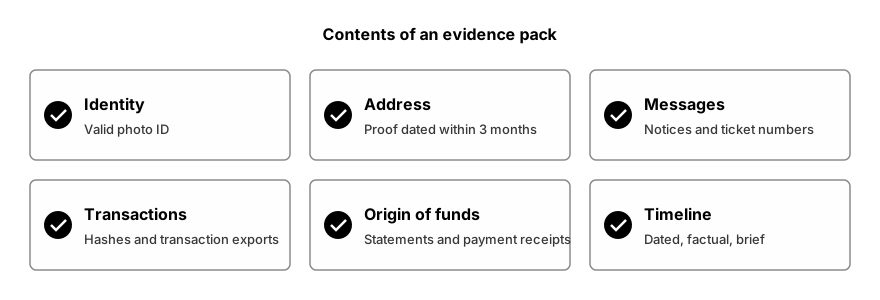
- Government-issued photo ID and address proof
- Card or account statements covering the period before the block
- Exchange records of the original purchase, plus the withdrawal that supplied the funds to the card account
- Bank statements tracing the source of the original funds
- Every notice or email the provider sent, plus the ticket reference numbers.
- For a business: your contracts, invoices, refund policy, plus a record of chargebacks filed against you recently
- Evidence that the sending wallet or exchange account is under your control.
- A brief written timeline showing when and how the funds were obtained.
What we cannot do
- We cannot compel a bank, card issuer or processor to restore an account or pay out a balance. The provider decides, inside its own rules and the law that applies to it.
- We cannot promise an outcome or a date. If we identify no realistic route, we decline the case.
- We refuse to change, backdate or fabricate a document, or to conceal the true origin of funds.
- Requests for a seed phrase, private keys, card PIN or passwords never come from us.
Common situations
- Card declined at every merchant after a top-up from a crypto exchange
- Bank account restricted following a large incoming transfer from a crypto platform
- Payment processor freezes the balance pending an extended review period
- Merchant account shut down after the business gets reclassified as high risk
- A sharp rise in chargebacks triggers a reserve or a termination notice
- Neobank sets a deadline for source-of-funds proof, then limits the account
- Account closed with notice that the provider no longer serves your activity type
This fits your case if
- Your crypto debit card ceased operation or was terminated without a stated reason.
- A bank or neobank froze or closed your account after incoming transfers from an exchange
- Your business accepts crypto payments, and the payment processor suspended you or held your balance
- A merchant account was terminated, and the provider demands documents you cannot yet assemble
- A short template email arrives, and the provider's actual request is unclear from it
How long it takes
Provider reviews take days or several weeks. Some processors hold funds for a fixed period even if the appeal succeeds. An estimate follows the assessment, and we update it as the case moves.
Fees
The assessment costs nothing. Its output is a written scope plus a fee model matched to your case type. No fee is requested before we have told you whether we can help. Fees →
Questions people ask
Why did a block hit my crypto card or bank account?
A block usually traces to one of these triggers: an unclear source of funds, a large or rapid transfer out of an exchange, a match against a high-risk category, or a chargeback pattern. The notice often states only a category name. To identify the real trigger, review your recent transactions and match them against each category.
Is a chargeback issue a different problem from a source of funds issue?
Yes, and the two need different responses. A chargeback issue concerns how often customers dispute payments; the fix is better dispute handling and clear refund terms. A source of funds issue concerns where the money came from; the fix is documents. Confusing the two wastes the appeal.
If the account is closed, can I still recover the balance?
Often the provider must explain how the remaining balance gets returned, but timing and conditions depend on the provider's policy; not verifiable from outside. Request the closure reason and the release process in writing, then keep the reply as evidence. We can help you frame that request.
Should I open a second account with the same provider?
Usually not. A second account can read as an attempt to bypass the block, and the provider may close that one too. Complete the appeal on the existing account first, and keep every step in writing.
Does a payment processor dispute require a lawyer?
Usually not in the first phase. Bring in a lawyer when three triggers appear: the processor holds a large balance, the appeal gets no response, or a contract clause is disputed. Legal steps are performed by independent licensed lawyers. We flag when that threshold is reached.
What can I do if the provider refuses to explain the block?
Some providers are restricted from sharing reasons, or choose not to. If the reason stays hidden, then act on what you control: prepare answers to the usual questions, assemble a clear source of funds pack, and request a named contact for the case. A complete pack often moves a stalled review forward.
Related situations
- Sourcing of funds and wealth: document packs. Build a clear source of funds and source of wealth pack for exchanges, banks and processors.
- Diagnosing a crypto freeze. Identify the party behind a freeze and the realistic next step.
- Procedure for Account Termination and Offboarding Management. Received a closure notice while your balance is still in? We draft written requests and escalate.
- Regulator and Ombudsman Filings. Construct a formal regulator, ombudsman, or consumer complaint including a precise timeline.
Read next
The content on this page is general. It is not legal advice.